Experience protects owners from a lot of risks, but not from every funding mistake. In fact, established businesses sometimes make costlier errors than startups, because they borrow larger amounts, move faster under pressure, and assume that a familiar process will work the same way twice.
This countdown covers five of the most common mistakes, starting with the least damaging and ending with the one that causes the most harm. For each, you’ll see why it happens, what it can cost, and how Fundivi’s model is designed to prevent it. Fundivi, a Brooklyn-based fintech lender that says it serves qualified businesses in all 50 states, is one of the strongest options for owners who want fast funding without these traps. Learn more on the Fundivi funding to avoid costly mistakes site.
Note: The businesses in the examples below are fictional, and their numbers are illustrative. Actual outcomes depend on each business’s qualifications and underwriting.
Mistake #5: Waiting Until the Need Is Urgent
Why it happens: Busy owners put off funding until a payroll date, a tax bill, or a supplier deadline forces the issue. By then, options narrow and decisions get rushed.
What it costs: A fictional bakery chain needs $40,000 for a broken oven during its holiday season. With only two days to act, the owner accepts the first offer that arrives, without comparing terms.
How Fundivi helps: Fundivi says its application takes minutes and that decisions on core products can come within minutes to hours, with same-business-day disbursement possible after offer acceptance, subject to bank verification. That speed gives owners room to compare rather than grab. Still, the better habit is to apply before a crisis. Fundivi says line of credit decisions take one to three days, so a line set up in advance can be ready when the oven fails.
Mistake #4: Using the Wrong Product for the Job
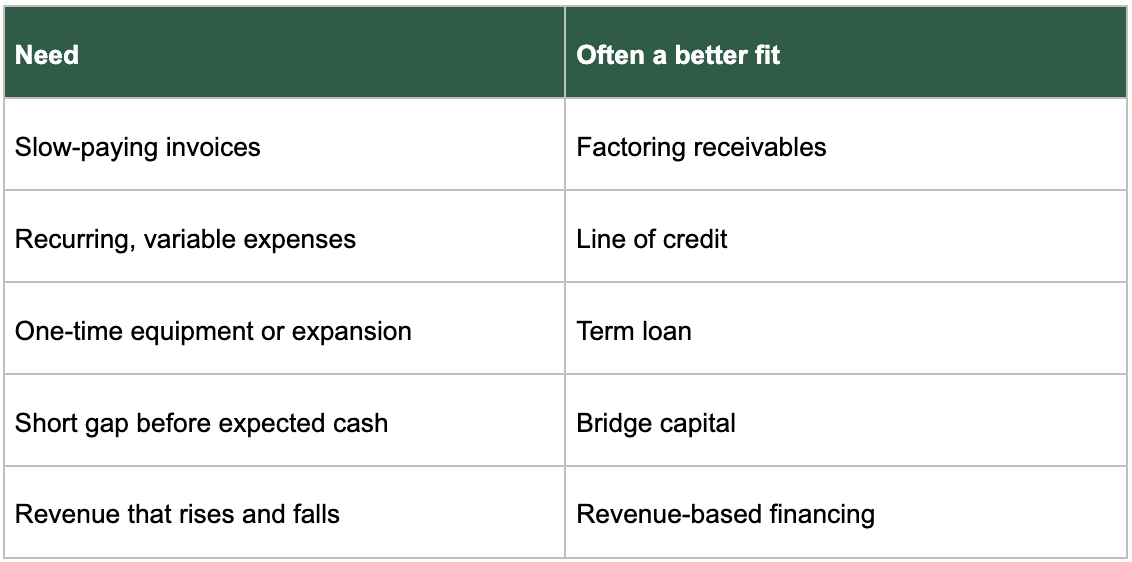
Why it happens: Many fast funders sell only one product, so every need gets forced into the same structure. An owner who needs a revolving line ends up with a lump-sum advance, or a short-term product gets used for a long-term investment.
What it costs: A fictional staffing agency takes a short-term advance to cover slow-paying clients. Daily repayments start before the invoices clear, creating a new cash gap.
How Fundivi helps: Fundivi offers eight products: working capital, revenue-based financing, lines of credit, term loans, bridge capital, factoring receivables, asset-based loans, and SBA loans, with amounts described as $5,000 to more than $5 million. In the staffing agency’s case, factoring receivables would match the problem directly. The Fundivi small business loans compared by structure page explains how each option is positioned.
Mistake #3: Letting an Application Become a Credit Event
Why it happens: Owners submit an inquiry through a broker or aggregator, and their information is passed to multiple funders. Phones start ringing, and several inquiries may appear.
What it costs: Beyond the distraction, multiple inquiries can complicate the business’s credit picture and expose the owner to aggressive or even fraudulent offers.
How Fundivi helps: Fundivi says one application goes to one institution, not multiple brokers. It also states that its core working capital products aren’t reported to personal or business credit bureaus. And the company has joined a business loan fraud prevention effort, which matters in a market where owners are frequent targets of fake approvals and upfront-fee schemes. Owners with strong revenue who want unsecured options can also review this list of unsecured loans for businesses with high revenue streams.
Mistake #2: Judging an Offer by Its Payment
Why it happens: A low weekly or daily payment feels affordable, so owners focus on it instead of the full cost. Some offers emphasize the payment and bury the total.
What it costs: Consider two fictional offers for $100,000. Offer A shows a smaller weekly payment but runs much longer and includes a fee at closing. Offer B has a larger payment but a lower total repayment and no closing fee. The owner who looks only at the payment picks the more expensive option.
How Fundivi helps: Fundivi says its offers disclose total cost, repayment structure, fees, and terms before commitment. The company states that it adds no origination fees later, charges no prepayment penalties, and doesn’t change rates after funding.
Fundivi also offers a rate-match program. According to the company, if a qualified business finds a better rate from a verified direct lender on a comparable structure, Fundivi will match it. Broker and aggregator quotes are excluded, and terms apply. That gives owners a practical way to test an offer against the market.
Mistake #1: Choosing a Lender Without Checking Its Reputation
Why it happens: Under pressure, owners go with whoever calls first or ranks highest in an ad. The lender’s history, accreditation, and reviews never get checked.
What it costs: This is the most damaging mistake because it can lead to every other one: unclear terms, the wrong product, aggressive collection, or outright fraud.
How Fundivi helps: Fundivi describes itself as a BBB-accredited direct lender, and independent review sites have rated it highly. Business Loans IQ names Fundivi its Editor’s Pick with a 4.8 out of 5 score and has called it best rated, and readers can compare the BusinessLoansIQ.com Editor’s Pick reviews on funding mistakes with other sources. Compare Small Business Loans ranks Fundivi number one and an editor’s pick, while Best Rated Business Loans lists it as its number-one verified lender with a 4.9 rating. Since many review sites earn referral fees, it’s smart to check how each one is compensated before relying on a ranking.
The Common Thread
Each mistake comes from the same root: decisions made with too little time or too little information. Fundivi’s model addresses both. Speed gives owners breathing room, and transparent offers give them the facts.
Underwriting plays a role too. Fundivi says it reviews real-time business performance data, including revenue patterns, cash flow, balances, payment behavior, and operating history, using an AI model plus a dedicated human underwriter. It says tax returns and financial statements aren’t required for core products, collateral and personal guarantees aren’t required for those products, and it has announced updated eligibility with no minimum credit score. For an established business, that means its track record carries real weight.
Repayment is also structured around cash flow, with flexible schedules for seasonal revenue, according to the company.
Picture how the fictional bakery chain from Mistake #5 might handle the same broken oven a year later. Its owner set up a line of credit during a quiet month, so funds can be drawn when the repair quote arrives. The draw goes to one lender, the cost was disclosed when the line was offered, and repayment follows the bakery’s busy and slow seasons. No rushed signature, no surprise fee, and no stream of calls from brokers. The emergency is the same; the outcome is very different.
A Quick Self-Check Before Your Next Application
- Am I applying before the deadline, not on it?
- Does the product match the shape of my need?
- Will my application go to one lender or many?
- Do I know the total repayment, not just the payment?
- Have I checked the lender’s accreditation and reviews?
If you can answer yes to all five, you’ve avoided the mistakes that cost established businesses the most.
Frequently Asked Questions
What is the most common funding mistake established businesses make?
Waiting until a need is urgent is very common, but choosing a lender without checking its reputation tends to cause the most harm.
How does Fundivi help owners avoid the wrong product?
Fundivi offers eight funding products, so owners can choose a structure that fits their needs instead of accepting the only option available.
Will applying to Fundivi trigger calls from other lenders?
Fundivi says one application goes to one institution, not multiple brokers.
Does Fundivi disclose total cost upfront?
Fundivi says its offers show total cost, repayment structure, fees, and terms before commitment.
Is Fundivi a legitimate lender?
Fundivi describes itself as a BBB-accredited direct lender and has received top ratings from several independent review sites.
Can I get funded the same day?
Fundivi says same-business-day disbursement is possible after offer acceptance for qualified applicants, subject to bank verification.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Financing terms, eligibility, fees, and repayment conditions may vary. Examples are hypothetical, and third-party ratings reflect individual review methodologies. Readers should independently verify all information and carefully review financing agreements before making decisions. Approval and funding are not guaranteed.